
How to Buy Term Life Insurance: Choose the Right Coverage
How to Buy Term Life Insurance: Choose the Right Coverage
Choosing term coverage starts with term length, typically 10 to 30 years, matched to financial obligations like a mortgage or years until kids become independent. Coverage amount should replace lost income and debts. Proper Life Insurance connects families with A+ rated carriers, including options requiring no medical exam.
Key Takeaways
- Term life insurance covers you for 10 to 30 years with affordable monthly premiums.
- Your beneficiaries receive a death benefit payout if you pass away during the policy term.
- Term policies provide the simplest, most cost-effective way to protect your family’s financial security.
- Proper Life Insurance helps Norman families compare coverage options and find the right term policy.
What Do You Need Before You Buy Term Life?
Three things matter most: a clear sense of income needs, a comfortable term length, and a willingness to compare carrier strength. Before families commit, they should understand how term life buying works and what the policy will and won’t do over time.
Term life pays a lump-sum death benefit to beneficiaries if the insured dies within a set period, usually spanning 10 to 30 years. Unlike permanent policies, term plans build no cash value and stop covering the insured once the term ends.
How Fast Can Coverage Start?
Many modern term plans skip the medical exam entirely, letting applicants qualify in minutes rather than waiting weeks for lab results. This makes affordable term insurance accessible to busy parents and first-time homeowners who need protection quickly, without needles or waiting rooms.
Families working through a term life buying guide should also confirm carrier financial strength. Proper Life Insurance partners only with A+ rated carriers. The coverage promise holds for the full length of the policy term.
How Do You Choose Coverage Amount and Term Length?
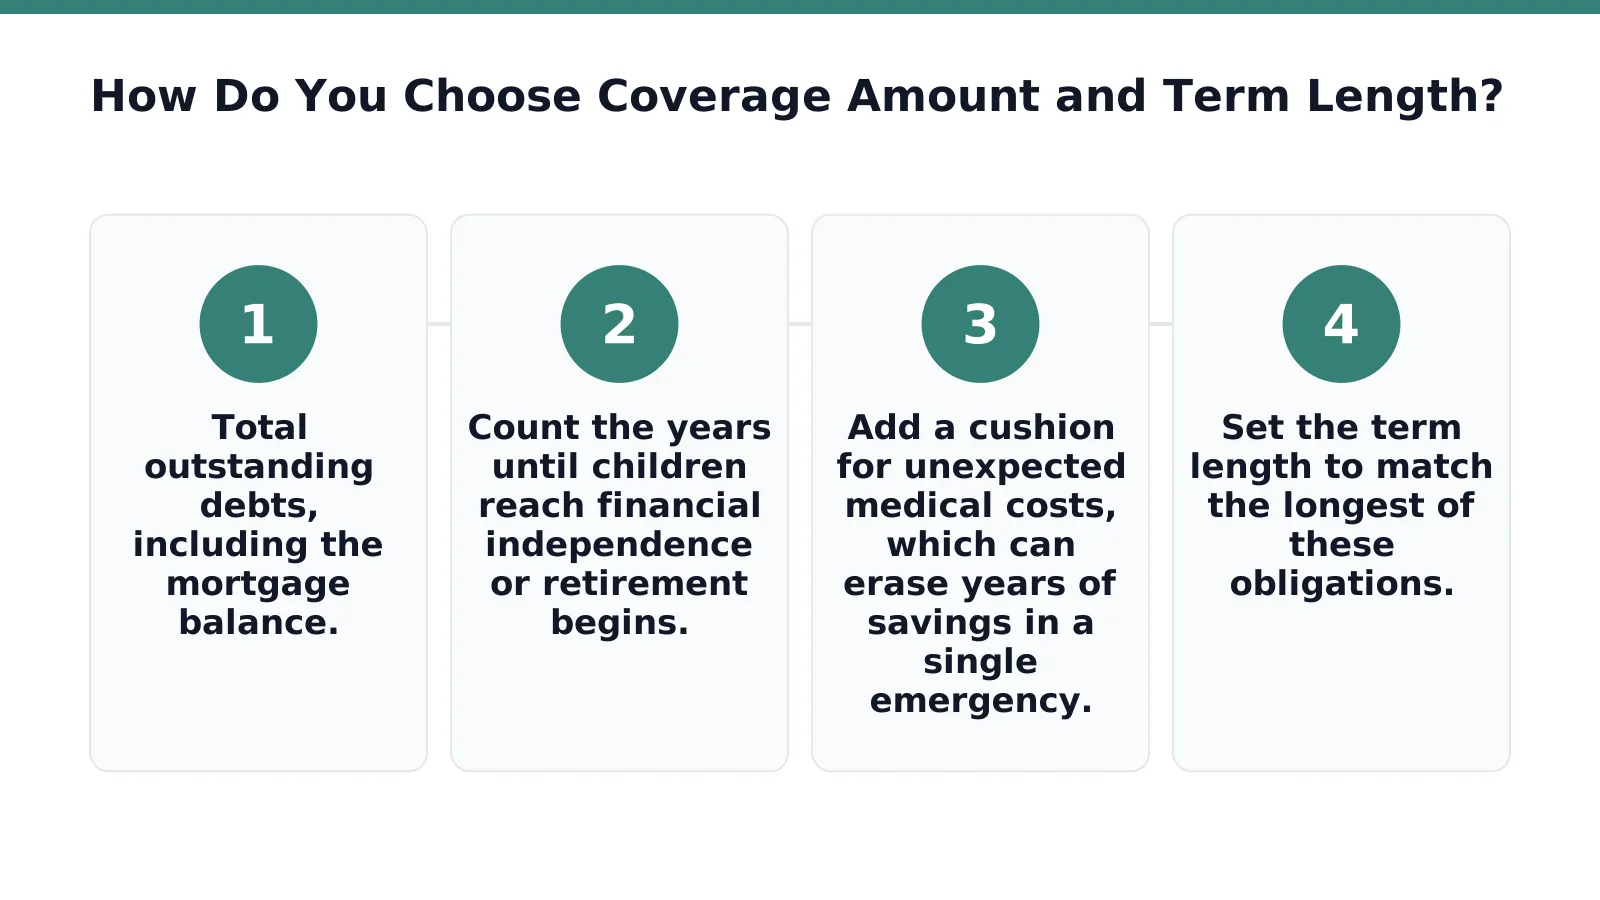
Coverage amount and term length depend on real obligations, not rough guesses. Families who buy term life coverage should size the death benefit around income replacement. Nearly half of households carry far less protection than needed to cover lost wages. A sound term life buying guide follows a clear sequence:
- Total outstanding debts, including the mortgage balance.
- Count the years until children reach financial independence or retirement begins.
- Add a cushion for unexpected medical costs, which can erase years of savings in a single emergency.
- Set the term length to match the longest of these obligations.
How much life insurance coverage is enough?
Coverage should mirror actual life circumstances, not a one-size template. Obligations like children’s education, a mortgage balance, and retirement timelines all shape the right payout number.
Is term life insurance actually affordable?
Many healthy adults overestimate how much term premiums actually cost. This misconception keeps many families from seeking genuinely affordable term insurance, even when delaying a purchase risks higher future premiums or lost eligibility.
What Mistakes Should You Avoid When Buying Coverage?
The biggest mistake is doing nothing at all. “7 Questions to Ask Before Buying a Term Life Insurance Policy” reports that 48% of all Americans carry no life insurance policy, leaving spouses and children financially exposed if an income earner dies unexpectedly. Beyond inaction, families shopping to buy term life coverage tend to repeat the same avoidable errors.
What are the most common term life buying mistakes?
A proper term life buying guide flags three recurring missteps:
- Treating the purchase as a one-time transaction instead of an ongoing relationship with a licensed advisor who revisits coverage after marriage, a new baby, or a home purchase.
- Choosing the cheapest affordable term insurance quote without reviewing payout adequacy.
- Working with a salesperson instead of an advisor who favors calm, pressure-free conversations over a hard pitch.
Does advisor support end after the policy is issued?
No. Families working with Proper Life Insurance’s licensed advisors, based in Norman, Oklahoma, keep access to ongoing support for future reviews and life milestones.
FAQ
How long does term life insurance coverage last?
Term life insurance typically covers you for 10 to 30 years, with the length matched to obligations like a mortgage or the years until children become financially independent.
How do I decide how much coverage to buy?
Total your outstanding debts, count the years until kids reach independence or retirement, and add a cushion for unexpected medical costs to size the right death benefit.
Do I need a medical exam to get coverage?
Many term plans skip the medical exam entirely, letting applicants qualify in minutes. Proper Life Insurance connects Norman families with A+ rated carriers offering these no-exam options.
Conclusion
In closing, choosing the right term life insurance coverage comes down to understanding your family’s financial needs, selecting an appropriate term length, and securing a policy that fits your budget. By taking time to evaluate your situation honestly and comparing options from A+ rated carriers, you gain the clarity and confidence needed to protect what matters most. Your family’s financial security is within reach, start your personalized review today and move forward with peace of mind.