
Life Insurance Cost Comparison: Understanding Premium Differences for High vs. Low Risk Factors
Life Insurance Cost Comparison: Understanding Premium Differences for High vs. Low Risk Factors
Life insurance is a crucial financial product that provides peace of mind and financial security for loved ones in the event of an untimely death. However, the cost of life insurance premiums can vary significantly based on several risk factors associated with the applicant. This article delves into the complexities of life insurance costs, particularly focusing on how high and low-risk factors influence premium rates. Readers will learn about the key risk factors affecting life insurance premiums, the underwriting process, and the cost differences between high and low-risk applicants. Additionally, we will explore strategies for high-risk individuals to find affordable life insurance options and provide real-life case studies illustrating these cost variations.
Understanding the nuances of life insurance costs is essential for making informed decisions. This article will guide you through the various elements that contribute to premium differences, helping you navigate the often confusing landscape of “life insurance”.
What Are the Key Risk Factors Affecting Life Insurance Premiums?
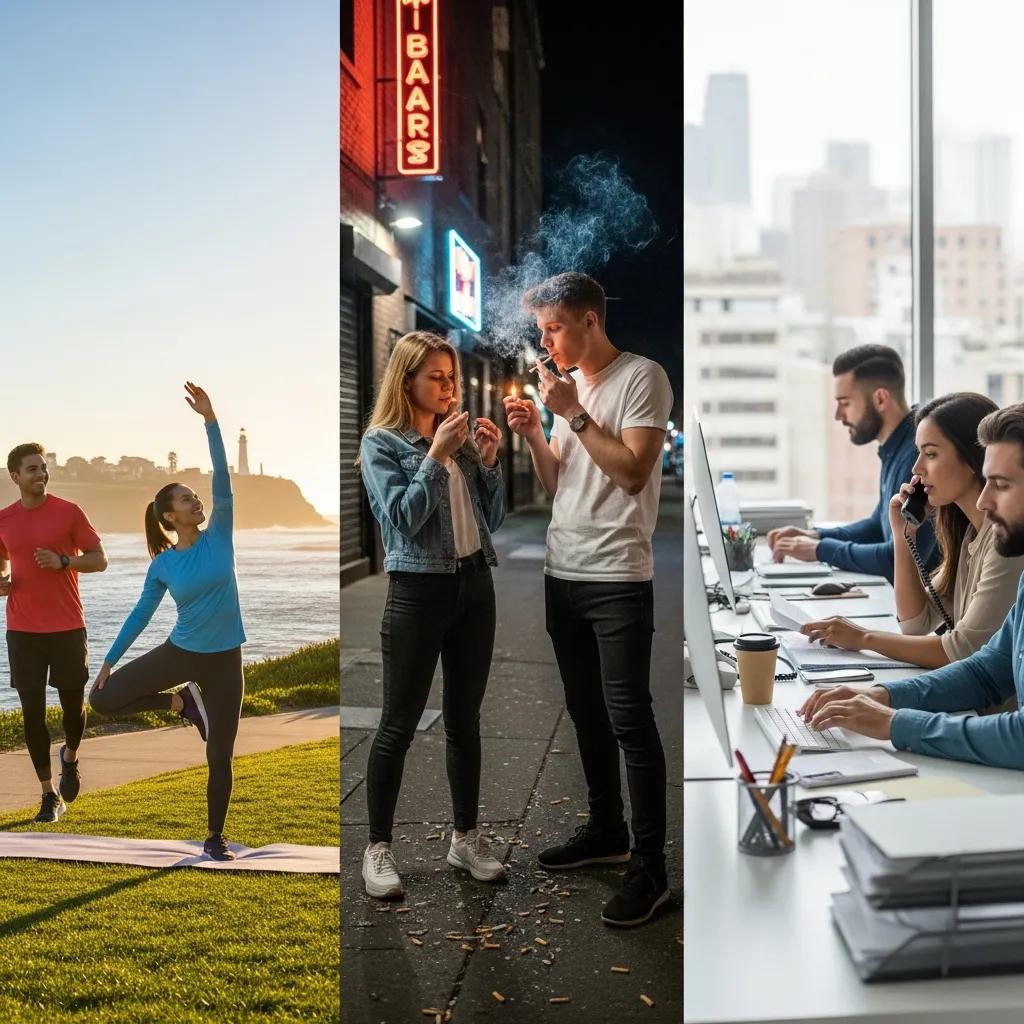
Several key risk factors significantly influence life insurance premiums. These factors include health conditions, lifestyle choices, age, and occupation. Insurers assess these elements to determine the likelihood of a policyholder making a claim, which directly impacts the premium amount.
How Do Health Conditions Influence Life Insurance Risk Classification?
Health conditions play a critical role in life insurance risk classification. Chronic illnesses, such as diabetes or heart disease, can raise an applicant’s risk profile, leading to higher premiums. Insurers often require medical examinations to evaluate an applicant’s health status, which can affect eligibility and pricing. Pre-existing conditions may also limit options for coverage, making it essential for individuals to disclose their health history accurately.
Indeed, research confirms that chronic illnesses significantly influence an individual’s risk profile in life insurance underwriting.
Life Insurance Underwriting: Chronic Illness Risk
The presence of pre-existing conditions, for example, diabetes, hypertension, asthma and other chronic illnesses led to a perceived high risk of early death. In addition, the experts used
A knowledge-based system for life insurance underwriting, MK Joram, 2017
Which Lifestyle Choices Increase Life Insurance Premiums?
Lifestyle choices significantly impact life insurance premiums as well. Engaging in high-risk activities, such as smoking or extreme sports, can lead to increased costs. For instance, smokers typically face premiums that are substantially higher than non-smokers due to the associated health risks. Additionally, factors like alcohol consumption and overall fitness levels can influence an insurer’s assessment of risk.
How Does the Underwriting Process Determine High and Low Risk Applicants?
The underwriting process is a crucial step in determining an applicant’s risk classification for life insurance. Insurers evaluate various criteria to assess the risk associated with each applicant, which ultimately influences premium costs.
What Criteria Do Insurers Use to Assess Life Insurance Risk?
Insurers utilize a range of criteria during the underwriting process, including health history, lifestyle choices, and occupational hazards. A comprehensive review of an client’s medical records, family history, and current health status helps insurers gauge potential risks. This assessment is vital for determining whether an applicant qualifies for coverage and at what premium rate.
How Does Underwriting Impact Premium Costs for Different Risk Profiles?
Underwriting directly impacts premium costs based on the risk profile established during the assessment. High-risk applicants, such as those with significant health issues or hazardous occupations, typically face higher premiums. Conversely, low-risk applicants benefit from lower rates due to their favorable health and lifestyle choices. Understanding this relationship can help individuals make informed decisions about their life insurance options.
This careful assessment is crucial, as an imbalance in risk evaluation can lead to unfair premium allocations.
Life Insurance Risk Assessment & Premium Fairness
With the conventional risk assessment technique, there is a danger of overcharging low-risk consumers while undercharging customers with high-risk profiles[2]. Accelerating the
Evaluation of risk level assessment strategies in life Insurance: A review of the literature, 2024
What Are the Cost Differences Between High Risk and Low Risk Life Insurance Premiums?
The cost differences between high-risk and low-risk life insurance premiums can be substantial. High-risk applicants often pay significantly more for coverage compared to their low-risk counterparts.
How Much More Do High Risk Applicants Typically Pay?
High-risk applicants can expect to pay anywhere from 50% to 100% more in premiums than low-risk applicants. This increase is primarily due to the higher likelihood of claims associated with their risk factors. Insurers calculate these costs based on statistical data and risk assessments, which highlight the financial implications of insuring high-risk individuals.
What Savings Can Low Risk Applicants Expect on Life Insurance?
Low-risk applicants enjoy considerable savings on their life insurance premiums. These individuals may benefit from lower base rates and streamlined underwriting processes, which can lead to more favorable terms. By maintaining a healthy lifestyle and avoiding high-risk behaviors, low-risk applicants can secure significant discounts on their premiums.
How Can High Risk Individuals Find Affordable Life Insurance Options?
Finding affordable life insurance can be challenging for high-risk individuals, but several strategies can help mitigate costs. Understanding the options available and taking proactive steps can lead to more favorable outcomes.
What Strategies Lower Premiums for High Risk Applicants?
High-risk applicants can employ various strategies to lower their premiums. Shopping around for quotes from multiple insurers is essential, as different companies may offer varying rates based on their underwriting criteria. Additionally, considering term life insurance instead of whole life insurance can provide more affordable options for those with higher risk profiles.
Are There Specialized Policies Tailored for High Risk Life Insurance?
Yes, some insurers offer specialized policies designed specifically for high-risk individuals. These policies may include higher premiums but can provide essential coverage for those who might otherwise struggle to find affordable options. Understanding the terms and conditions of these specialized policies is crucial for making informed decisions.
What Real-Life Case Studies Illustrate Cost Variations by Risk Profile?
Real-life case studies can provide valuable insights into how different risk profiles affect life insurance premiums. By examining specific examples, individuals can better understand the financial implications of their health and lifestyle choices.
How Do Smoking and Chronic Illness Affect Life Insurance Premiums?
For instance, a smoker may face premiums that are 50% higher than a non-smoker due to the increased health risks associated with smoking. Similarly, individuals with chronic illnesses may find themselves categorized as high-risk, leading to elevated costs. These examples highlight the importance of health and lifestyle in determining life insurance premiums.
What Are Examples of Premium Savings for Low Risk Applicants?
Conversely, low-risk applicants can experience substantial savings. For example, a healthy non-smoker in their 30s may secure a policy for as little as $20 per month, while a smoker of the same age could pay upwards of $50 or more. These case studies illustrate the significant impact of risk factors on life insurance costs.
What Tools and Resources Help Compare Life Insurance Costs by Risk Factors?
Several tools and resources are available to help individuals compare life insurance costs based on risk factors. Utilizing these resources can aid in making informed decisions about coverage options.
How to Use Life Insurance Cost Calculators for Personalized Estimates?
Life insurance cost calculators are valuable tools that allow individuals to input their specific information and receive personalized premium estimates. By providing details such as age, health status, and lifestyle choices, users can gain insights into potential costs and coverage options.
Where to Find Up-to-Date Statistics and FAQs on Life Insurance Risk and Cost?
Reliable sources for up-to-date statistics and FAQs on life insurance risk and cost include industry reports and government resources. These sources provide valuable insights into current trends and help individuals stay informed about the life insurance landscape.
Different risk factors significantly influence life insurance premiums, leading to varying costs for high-risk and low-risk applicants. Understanding these factors and utilizing available resources can empower individuals to make informed decisions about their life insurance needs.